1. Introduction: The High-Stakes World of Contractor Exits
Between early 2023 and 2025, the number of active private equity-backed roofing platforms in the United States tripled from 17 to 56. Driven by institutional capital, strategic consolidators, and aggressive roll-up strategies across Western states—including California, Arizona, Colorado, Nevada, Oregon, and Washington—transaction volumes reached all-time highs. Industry estimates now value the national roofing market at anywhere from $50 billion to $100 billion, creating an unprecedented consolidation wave where valuation multiples sit near historical peaks.
For founder-operators, this momentum suggests an unparalleled opportunity to cash out. However, the operational and financial realities beneath the surface tell a far more complex story. While headline enterprise values make for impressive news, the actual mechanics of closing a roofing deal are filled with counter-intuitive traps, strict regulatory barriers, and hidden financial haircuts.
As buyers shift toward integration discipline, cost scrutiny, and rigorous underwriting in 2025, 2026, and 2027, navigating a business exit requires moving beyond vanity metrics. Here are five surprising realities every contractor and investor must understand before taking a roofing business to market.
2. Takeaway 1: The “Headline Multiple” Illusion — Why Cash at Closing Falls Well Below Valuation
The top-line valuation agreed upon in a Letter of Intent (LOI) is rarely the amount that lands in a founder's bank account on closing day. Founders who focus exclusively on a top-line Enterprise Value (EV) frequently face a stark reality check when structural deductions, holdbacks, and working capital pegs are applied.
Consider a middle-market proceed bridge modeled by advisory firm Auxo Capital Advisors. While the company achieved an impressive headline Enterprise Value of $8.25 million, the actual pre-tax cash delivered at close dropped to $6.20 million—a reduction of nearly 25%.
| Proceed Bridge Component | Financial Value | Impact on Cash at Closing |
|---|---|---|
| Headline Enterprise Value (EV) | $8,250,000 | Top-line purchase price agreed in Letter of Intent (LOI) |
| Funded Debt Retirement | -$900,000 | Deducted dollar-for-dollar to pay off equipment loans & credit lines |
| Indemnity & Warranty Escrow | -$400,000 | Deferred cash held back for potential workmanship & legal claims |
| Net Working Capital (NWC) Shortfall | -$250,000 | Deducted dollar-for-dollar due to deficit relative to target NWC peg |
| Rollover Equity | -$500,000 | Non-cash reinvestment retained as illiquid equity in buyer entity |
| Net Pre-Tax Cash at Close | $6,200,000 | Delivered pre-tax liquidity to seller at closing (-24.8% vs. Headline EV) |
| Contingent Earnout | $300,000 | Uncertain post-close payout tied to backlog conversion milestones |
This substantial gap occurs because buyers treat structural deal items as non-negotiable risk mitigators. Funded equipment loans and lines of credit are wiped clean at closing, directly reducing net proceeds. Meanwhile, buyers protect themselves against unbilled work-in-progress (WIP), broken equipment, or aged payables through strict Net Working Capital pegs, while setting aside escrow holdbacks to buffer against post-closing warranty claims. Furthermore, platforms routinely require founders to accept rollover equity, forcing them to exchange upfront liquid cash for illiquid minority paper in the acquiring parent entity.
Founders often misinterpret Enterprise Value as guaranteed cash. Defining target working capital baselines, auditing accounts payable, and addressing equipment deficiencies before signing an LOI prevents painful, last-minute purchase price adjustments during financial diligence.
3. Takeaway 2: The Recurring Revenue Goldmine — B2B Maintenance Contracts Outshine One-Off Work
In roofing M&A, two companies with identical top-line revenues can command drastically different price tags based entirely on their revenue mix. Buyers do not value all revenue equally; predictable, contracted service agreements command a massive premium over lead-dependent residential replacements.
Commercial preventive-maintenance contracts—servicing warehouses, healthcare facilities, retail centers, and multi-family properties—typically yield high gross margins (40% to 60%) and strong EBITDA margins (around 25%). When annual client retention exceeds 90% (less than 10% churn), buyers price these streams like recurring technology revenue, valuing them at 2.0x to 3.5x Annual Recurring Revenue (ARR). Mathematically, this translates to an implied 8x to 14x EBITDA multiple on that specific service book.
Comparative Valuation Study: Revenue Mix Impact Across Identical Scale (Auxo Capital Advisors)
- Commercial Reroofing: 65% of Revenue
- Contracted Maintenance / Service: 20% of Revenue
- Residential Roofing: 15% of Revenue
- Residential Replacement: 75% of Revenue
- Storm Restoration: 20% of Revenue
- Repair & Service: 5% of Revenue
Private equity buyers view contracted B2B maintenance books as “software-like” annuity streams that guarantee post-close stability. By spending 12 to 24 months building a commercial service book, an owner can expand their company's blended valuation multiple by 1.5x to 2.5x turns of EBITDA without adding single-shot construction risk.
4. Takeaway 3: The Storm Trap — Why Weather Spikes Trigger Heavy Underwriting Discounts
While a major storm event can lead to record-breaking annual profits for residential and restoration contractors, sophisticated buyers treat weather-driven spikes with extreme skepticism.
Rather than applying top-tier platform multiples to a peak earnings year driven by hail or wind damage, acquirers normalize EBITDA over multi-year cycles. If storm and insurance-restoration claims represent more than 50% of a company’s revenue, buyers routinely impose a 1.0x to 2.0x multiple discount, pricing the business at a lower 2.5x to 4.0x EBITDA band.
Quality of Earnings (QoE) Underwriting Consensus Multi-Year Normalization“Weather-driven insurance claim surges create artificial ‘waves’ in EBITDA that buyers refuse to value as permanent run-rate earnings.”
Operators who experience a massive storm-driven revenue surge often attempt to sell at the top of the curve. However, institutional buyers easily strip out these temporary gains during Quality of Earnings (QoE) audits. To capture top-dollar valuations, restoration operators must demonstrate preferred-vendor status with major insurance carriers or diversify into steady reroofing and repair work.
5. Takeaway 4: Regulatory Landmines — How State Licensing Rules Can Stop a Deal Cold
Across Western jurisdictions—where state licensing frameworks represent critical deal structure gates—regulatory hurdles can halt an M&A transaction regardless of buyer enthusiasm or agreed purchase price. California serves as the primary regional benchmark for these regulatory complexities.
Why Asset Sales Void Contractor Licenses Under CSLB Section 7075.1
Under California Business and Professions Code Section 7075.1, a Contractors State License Board (CSLB) license belongs strictly to the specific corporate entity and cannot be sold, assigned, or transferred in an asset purchase. If a transaction is structured as an asset sale (where the buyer purchases equipment, contracts, and brand name without buying the corporate shell), the seller's license is voided for that deal. The buyer must already hold or obtain an independent CSLB C-39 license, post new bonds, and submit workers' compensation filings before closing escrow and executing work. Consequently, state licensing constraints across the West often force transactions into stock sales to preserve operating continuity.
Furthermore, qualifier succession represents a severe legal compliance risk throughout the region:
1. The “Renting” Trap
Under California Business and Professions Code Section 7068.1(e), a Responsible Managing Officer (RMO) or Employee (RME) must actively participate in operational control. “Renting” an exiting founder’s license post-close without real operational oversight is a misdemeanor, punishable by license revocation, fines up to $5,000, and up to six months imprisonment.
2. SBA Loan Constraints
Small Business Administration (SBA) lending guidelines explicitly prohibit a selling founder from remaining on indefinitely to act as the post-closing license qualifier for the buyer—Frequently derailing unvetted SBA-backed buyers mid-escrow.
3. The Internal Succession Fix
Founders planning a stock sale can bypass licensing friction by elevating a supervising employee who has been with the firm for at least five years. Under California law, such internal candidates can replace a retiring qualifier without taking trade licensing exams.
Regulatory hurdles often dictate whether a transaction must be structured as a stock sale or an asset sale. Owners across Western states who audit their entity structures and establish internal license qualifiers 18 to 24 months before going to market prevent severe closing delays or legal non-compliance.
6. Takeaway 5: The Auction Premium — Single-Buyer Negotiations Cost Founders Millions
When contacted directly by an aggressive private equity firm or strategic platform, founders are often tempted to negotiate exclusively in a direct, off-market deal. However, entering single-buyer negotiations frequently leaves significant capital on the table.
EBITDA multiple premium achieved in structured, competitive processes targeting both strategic and financial buyers.
Average final enterprise valuation increase in advisor-led competitive auctions vs. proprietary single-buyer deals.
Increase in transaction closing probability when backup bidders prevent a lone acquirer from re-trading the LOI.
Advisory data from Mainstreet Wealth and transaction metrics from the Axial marketplace confirm that running a structured, competitive sale process targeting both strategic acquirers and financial buyers yields a 1.0x to 2.0x EBITDA multiple premium, roughly 25% higher final valuations, and a 75% higher closing probability compared to proprietary, single-buyer negotiations.
Professional buyers actively seek proprietary, non-competitive deals to acquire quality companies at single-digit multiples before market forces come into play. Creating a competitive environment forces buyers to pay for future growth potential rather than buying on the cheap.
7. Key Benefits of a 12-to-24 Month Exit Runway & The Cortland Operator-Broker Advantage
For founders and owner-operators planning an exit over the next 12 to 24 months, initiating preparation early provides a substantial financial and strategic advantage. With institutional buyers and private equity platforms actively consolidating Western contractors and industrial service providers, a structured 12-to-24-month runway allows owners to maximize enterprise value, streamline diligence, and protect net cash proceeds.
1. Expanding Valuation Multiples & Recurring Revenue Mix
Transitioning sales focus toward high-margin commercial preventive maintenance contracts can expand blended enterprise valuation multiples by 1.5x to 2.5x EBITDA turns. Commercial contracted maintenance commands premium multiples (2.0x–3.5x Annual Recurring Revenue or an implied 8x–14x EBITDA) due to predictable recurring cash flow.
2. Bridging the Gap Between Headline Valuation and Cash at Close
Headline enterprise value rarely equals delivered cash at close due to debt deductions, working capital pegs, warranty escrows, and earnout holdbacks. Preparing 12 to 24 months out allows owners to reconcile receivables/payables, optimize field equipment, and set target Net Working Capital (NWC) levels to prevent last-minute purchase price write-downs.
3. Resolving State Licensing and Regulatory Bottlenecks
In states like California, statutory rules (such as CSLB Section 7075.1) prohibit transferring contractor licenses across business entity changes during asset sales. A multi-month runway gives founders time to corporate-structure appropriately or elevate a five-year supervising employee to serve as Responsible Managing Employee (RME) or Officer (RMO), eliminating license-transfer friction without locking the founder into multi-year employment obligations.
4. Eliminating Founder Dependency & Audit-Proofing Financials
Delegating estimating, purchasing, and customer account management to salaried managers proves the business can operate independently of the founder. Shifting from cash to accrual job costing and formalizing Work-in-Progress (WIP) schedules ensures financial records easily pass rigorous Quality of Earnings (QoE) audits.
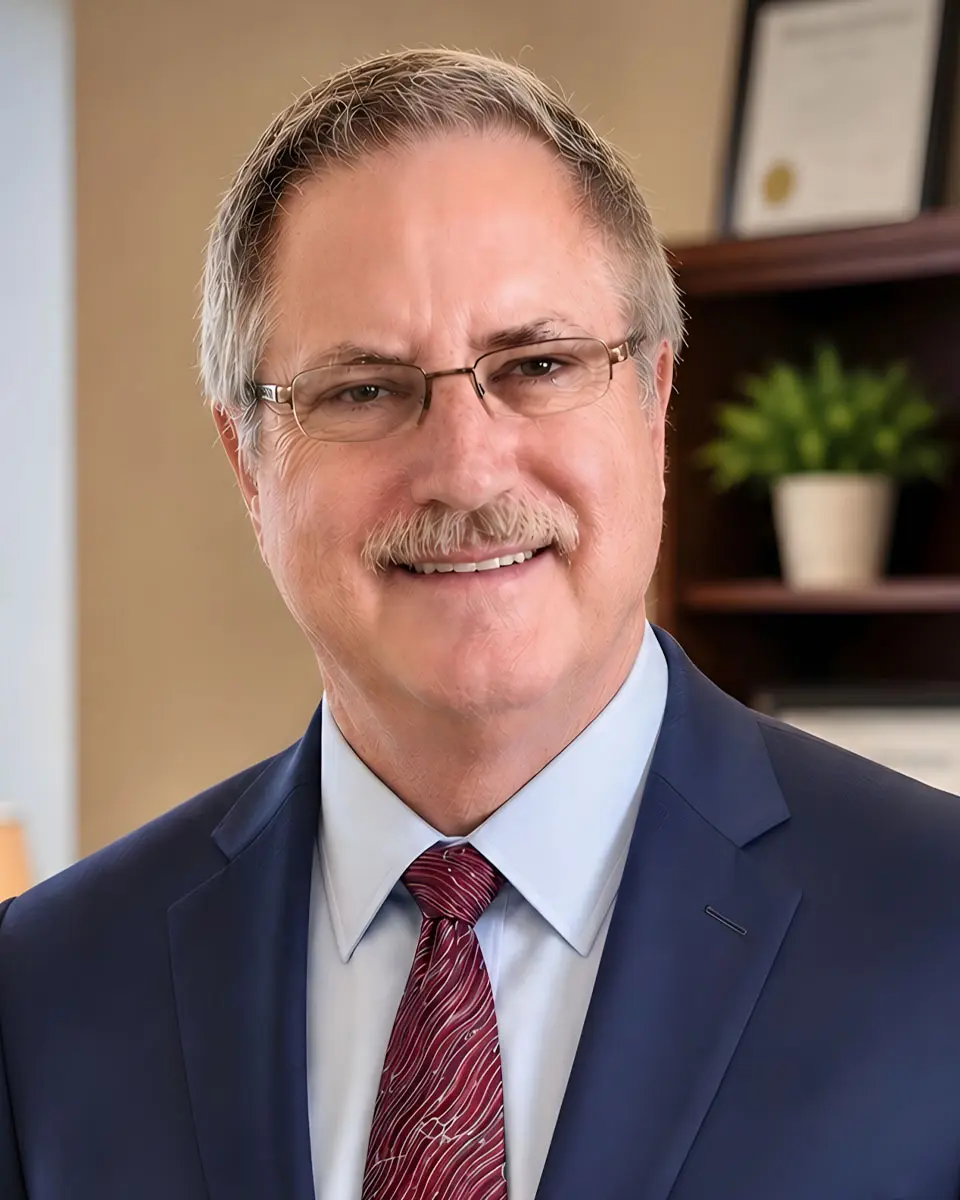
How Stan Cortland & Cortland Business Brokers Help Roofing Founders Exit at Peak Value
Cortland Business Brokers addresses common M&A friction points through an operational and seller-focused advisory framework designed specifically for lower-middle-market contractors across California and our 6-state Western footprint:
Founder Stan Cortland brings over 37 years of sales, executive management, and principal business ownership—including scaling and running one of the top three largest Xerox dealerships in the US. As an “Operator-Broker,” he approaches advisory with real-world operational fluency, understanding payroll pressures, field mechanics, and founder exit fatigue.
Purely financial brokers often miss operational value. Cortland evaluates field service logistics, fleet efficiency, commercial maintenance contract quality, and customer acquisition funnels to quantify intangible assets and build a defensible, audit-ready valuation.
Operating across a 6-state Western footprint, Cortland connects California and regional business owners with out-of-state private equity firms, strategic consolidators, and capital-rich buyers. Running an advisor-led competitive process with multiple buyers yields an average 1.0x to 2.0x EBITDA multiple premium.
To combat the widespread ~70% industry deal-failure rate, Cortland uses in-house underwriting literacy to pre-qualify buyers against strict SBA and commercial lender guidelines—including license qualifier rules—before granting exclusivity.
Cortland structures transactions to maximize net after-tax proceeds rather than just top-line numbers—mitigating heavy California tax burdens (such as the 13.3% state capital gains rate and Form 593 3.33% withholding via IRS Section 453 installment structuring), balancing transition timelines, and protecting employee legacy.
Implements blind-teaser protocols, binding CABB NDAs, and 24–48hr Proof of Funds screening to protect crew stability, customer relationships, and trade secrets. Cortland operates on a 100% success-based commission structure ($0 upfront retainers) and offers complimentary, no-obligation business valuations.
8. Conclusion: Navigating the Exit Horizon
The Western US roofing market remains mid-stride in a historic consolidation wave, but the era of easy, unexamined exits has drawn to a close. As consolidators pivot toward operational integration, technology adoption, and strict financial traceability, the valuation gap between unprepared businesses and institutional-quality platforms is widening.
Winning an exit in today's market requires clear job-costing financial records, non-transferable licensing continuity, diversified revenue books, and competitive deal design.
As you evaluate your business's 12- to 24-month horizon, ask yourself one question: Is your operation structured to command a platform premium, or will unaddressed friction points leave millions of dollars on the closing table?
Claim Your Confidential, No-Cost Normalized SDE/EBITDA Valuation
Speak directly with Principal Advisor Stan Cortland to benchmark your roofing company's adjusted EBITDA, B2B service contract multiple expansion, CSLB C-39 succession posture, and institutional buyer demand across our 6-state Western network.
Discovery Bay, CA 94505